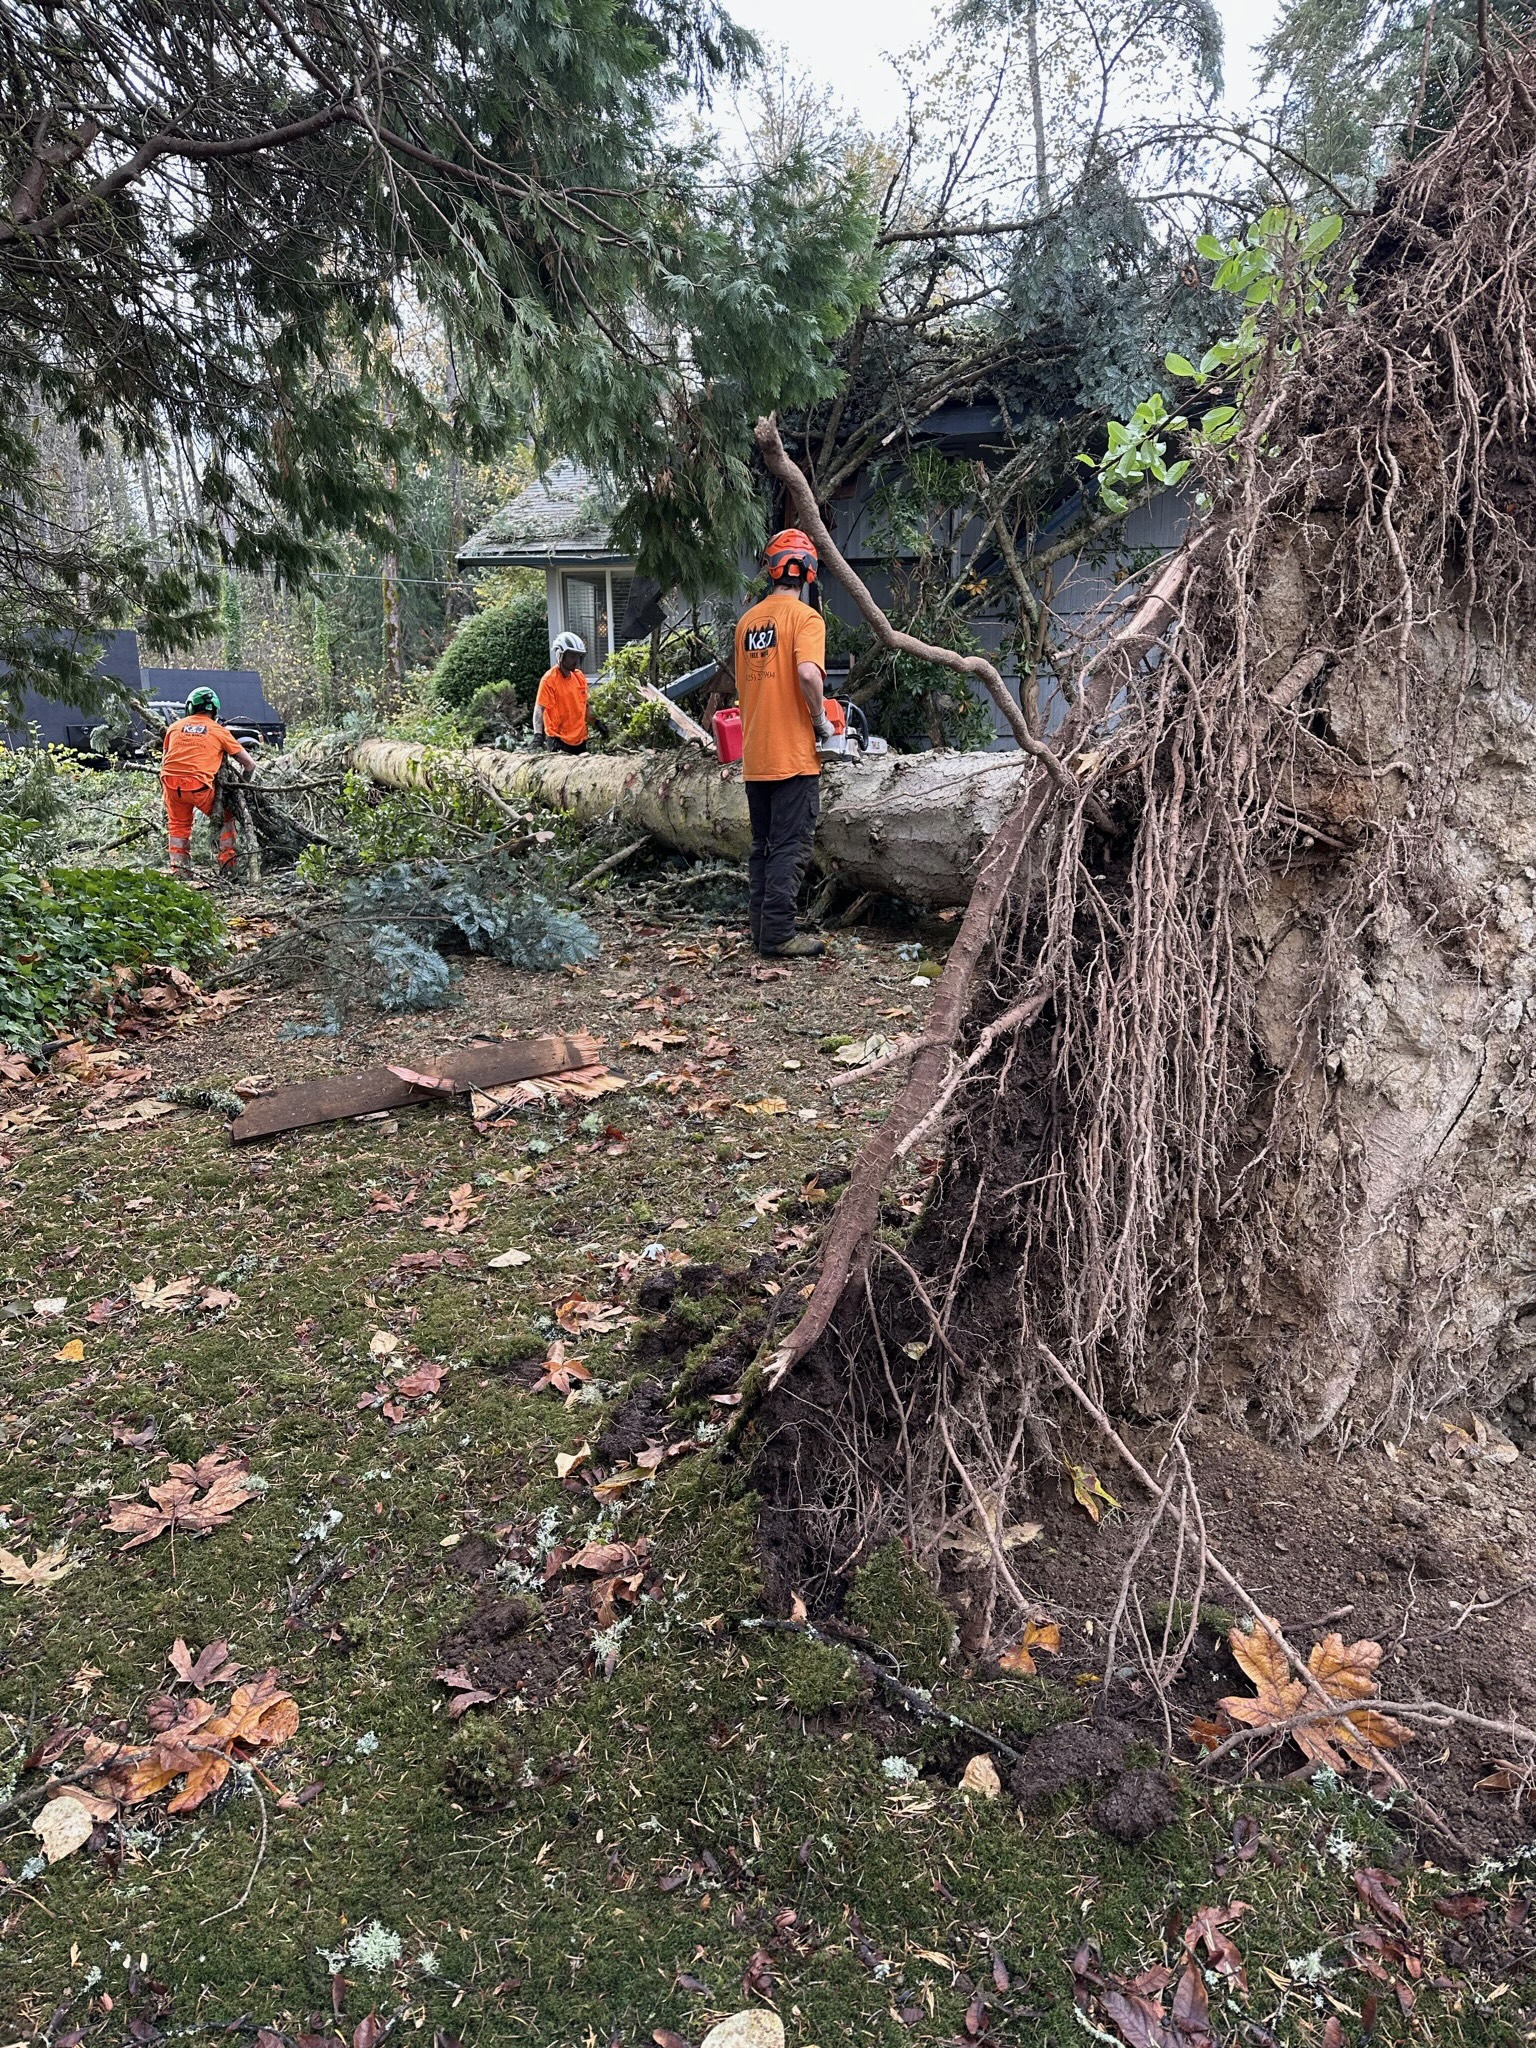
Tree Fell on Your House? Storm & Insurance
Snohomish & King County, WA — January 23, 2026
What to do when a storm drops a tree in Snohomish or King County: first safety steps, utility contacts, what insurance usually covers, Washington claim rules, and how K&J documents the tree work.
WarningCall 911 first if anyone is hurt or trapped, a wire is sparking or burning, a line is touching an occupied vehicle, or you smell gas. Treat every downed wire as live and keep well back — Puget Sound Energy advises at least 35 feet, about the length of a school bus.
Last reviewed: October 23, 2026. This guide is general information for homeowners in Snohomish and King County, not legal advice or a coverage decision.
First steps after a tree falls
- Get everyone out of the damaged part of the house. A tree on a roof can shift, and damaged framing may not hold. Do not go back in to look at the damage.
- Treat every wire as live. Cable and phone lines can be touching power lines. Stay back and call your electric utility (see the table below).
- Do not cut, climb or pull on the tree. Trunks and limbs pinned under weight can spring back or roll when cut. Leave roof work and rigging to a tree crew.
- Take photos or video from a safe spot. Wide shots of the tree, the damage and the surrounding area are enough. Never approach a hazard for a picture.
- Limit further damage only if it is safe. Move belongings away from leaks and catch water indoors. Washington's Insurance Commissioner advises saving receipts for temporary repairs such as tarps and plywood, and not making permanent repairs until your insurer has seen the damage and you have agreed on repairs.
- Call your insurer or agent. Report the damage promptly and ask what they need from you. The questions further down this page are a good starting point.
- Call a tree service. Once the utility has made any lines safe, a tree crew can plan how to take the tree off the house without causing more damage.
Tree on a Power Line? Who to Call, by Utility
Only the utility can make its lines safe. Nobody — including a tree crew — should work on a tree touching a line until the utility says it is safe. Your utility's name is on your electric bill.
| Utility | Communities we serve | Downed line or outage |
|---|---|---|
| Snohomish County PUD | Snohomish County, including Everett, Lynnwood, Edmonds, Marysville, Monroe and Sultan | Call the PUD at 425-783-1001. Also call 911 if the line is sparking, burning or touching an occupied vehicle. |
| Puget Sound Energy | King County communities including Kenmore, Bothell (King County side), Woodinville, Redmond, Duvall and Carnation | Call 911 or PSE at 1-888-225-5773. |
| Seattle City Light | Shoreline | Downed line: call 911. Outage: 206-684-3000. |
Puget Sound Energy advises staying at least 35 feet from a downed line; Snohomish County PUD and Seattle City Light say at least 30 feet. Utility crews focus on their equipment and restoring power, so ask what they will remove and what they will leave. Anything left on your property is generally yours to arrange.
Tree across a public road? Call 911 if it is an immediate danger to traffic. Otherwise, report it to the agency that maintains the road: your city for city streets, Snohomish County Road Maintenance for unincorporated Snohomish County, or the King County 24/7 Road Helpline at 206-477-8100 for unincorporated King County.
What homeowners insurance usually covers
Coverage depends on your policy, the cause of the damage, what the tree hit, your deductible and limits, and your insurer's decision. The patterns below come from the Insurance Commissioner's winter-weather guidance. They are common outcomes, not guarantees.
| Situation | What usually happens | Ask your insurer |
|---|---|---|
| Tree damages your home, garage or another covered structure | Damage from falling trees is usually covered, and removal from the structure may be included, subject to your deductible and limits | How much tree removal is included, and is there a separate limit? |
| Tree falls in the yard and hits nothing | Removal and cleanup usually are not covered | Does my policy cover removal when a tree blocks a driveway or an accessibility ramp? |
| A neighbor's tree falls on your house | Your own homeowner insurer will often pay, minus your deductible. Recovering money from the neighbor's insurer usually requires showing the neighbor was at fault, which can be hard to prove | Will you seek recovery from the neighbor's insurer, and could that return my deductible? |
| Tree damages your car | Comprehensive auto coverage, if you carry it, should cover the car. It has its own deductible | Is the car handled as a separate claim? |
| A damaged tree is still standing | Removing a tree before it falls is often not covered | Is any part of this removal covered because of the storm damage? |
Removing the tree from your house vs. hauling it away
Many policies treat these as two separate costs. Getting the tree off the damaged structure so it can be repaired is often handled as part of the claim for your home. Cutting up the wood and hauling it off your property usually has a separate, smaller limit. In the standard industry policy form, that limit is $1,000 per storm, with no more than $500 for any one tree. Some insurers set it higher; PEMCO's policy allows up to $2,000. Not every insurer splits the costs this way, so ask your adjuster before work starts. The NW Insurance Council also notes that coverage and limits for debris removal vary.
Filing a claim can affect your premium or renewal. The Insurance Commissioner notes that you can ask your insurer whether a loss is covered without filing a claim, and that a small loss close to your deductible may not be worth claiming.
How the insurance claim process works in Washington
- Report the loss and ask questions. Use the list below so you know what your insurer needs before work starts.
- Document the damage safely. Keep photos, estimates, receipts and copies of everything you send.
- Send a written scope for urgent work. Under Washington rules that took effect October 18, 2026, when your policy requires you to protect your property from further damage, your insurer must approve your mitigation scope, or give you its own approved scope, within five business days after receiving it (WAC 284-30-330). That is a deadline for a response to the scope, not a payment deadline or automatic approval. Do not wait on work needed to keep people safe; tell your insurer what is happening and keep records.
- Expect an inspection and decision. Your insurer may send an adjuster, contractor or other professional. Washington rules generally require insurers to acknowledge a claim within 10 business days and to accept or deny it within 30 days, or explain in writing why they need more time. The Insurance Commissioner's guide to filing a homeowner insurance claim explains these rights.
- Submit the invoice and receipt. Your insurer decides what it pays. For example, if a $3,000 tree removal were the only approved item and your deductible were $1,000, the payment could be $2,000 — assuming no other limits or adjustments apply and the deductible has not already been applied elsewhere in the same claim.
- If you disagree, ask for the reason in writing. Washington rules require insurers to explain denials and compromise offers with reference to the policy. The Insurance Commissioner's consumer advocates can help at 800-562-6900 (weekdays, 8:30 AM–4:30 PM).
Questions to ask your insurer
- What emergency work can you authorize now?
- Where should I send a written scope for the urgent tree work?
- What photos, estimates or receipts do you need?
- What is my deductible, and do any limits apply to tree removal?
- Can any approved amount be paid before all the work is finished?
- Will my mortgage lender be named on the check?
How K&J Tree Works helps with insurance-related tree work
K&J Tree Works provides a written scope and estimate, followed by a contract, invoice and receipt. These documents give you a clear record of the tree work to share with your insurer. When a tree is on a structure, our invoice lists removing it from the structure separately from cutting it up and hauling it away, so your insurer can see each part of the work.
We typically do not communicate directly with insurance adjusters. You handle your claim with your insurer, while we handle the agreed tree work.
Clients usually pay K&J's invoice and submit their documentation to their insurer for review and any reimbursement available under their policy. Your insurer determines coverage and payment. Deductibles, limits, exclusions and approved charges can affect what you receive, and reimbursement is not guaranteed.
What to expect when you call
- Call (425) 223-7904. We take calls 24/7. We ask about injuries, power lines and whether the tree is on an occupied structure. Life-safety emergencies go to 911 first. When we can be on site depends on safety conditions, storm demand and crew availability, so we do not promise a set arrival time. Regular business hours are Monday–Saturday, 8 AM–5 PM.
- On-site assessment. We look for secondary hazards such as hanging limbs, trunks under tension and other damaged trees, then explain the removal plan.
- Written scope, estimate and contract before work begins.
- Controlled removal. When a tree is on a structure, we take the weight off in sections and lower pieces with rigging instead of dropping them onto a damaged roof. Roof and building repairs are a separate job for a roofer or general contractor, and K&J does not provide stump grinding.
- Invoice and receipt when the work is complete.
Learn more about our emergency tree service across Snohomish and King County.
Hiring help after a storm
- Verify the contractor. Check registration with Washington L&I. Its Hire Smart steps recommend written bids, a detailed contract and written payment terms.
- Be wary of insurance promises. Nobody but your insurer can tell you what your policy will pay.
- Think before signing an "assignment of benefits." The Insurance Commissioner warns that this form can let a contractor negotiate and settle your claim with your insurer without your approval. A normal work agreement should not hand over control of your claim.
Do you need a permit to remove a storm-damaged tree?
Rules depend on whether the property is in a city or in unincorporated county, and whether critical areas such as wetlands, streams, steep slopes or their buffers are involved. Some codes allow urgent work on an immediate threat before approval but still expect follow-up. For example, Everett's critical areas code exempts emergency actions needed to address an immediate threat, as verified by the city, and requires impacts to critical areas to be mitigated within one year. Take before-and-after photos and contact your city or county planning department as soon as you practically can. Our tree removal guide explains how to find the right jurisdiction.
Before the next storm
- Sign up for emergency alerts: SnoCoAlerts in Snohomish County or ALERT King County.
- Learn the warning signs in our fall and winter tree-risk guide.
- If a tree near your home worries you, schedule a hazard tree assessment before the next windstorm.
- After the emergency is handled, our storm cleanup guide covers wood and debris options.
Storm Tree Emergency and Insurance Questions
- Who do I call if a tree falls on a power line?
- Call your electric utility, and call 911 if the line is sparking, burning or touching an occupied vehicle. In Snohomish County that is Snohomish County PUD (425-783-1001). In the King County communities we serve outside Shoreline, it is usually Puget Sound Energy (1-888-225-5773). In Shoreline, call 911 for a downed Seattle City Light line. Stay well back and do not let anyone work on the tree until the utility says it is safe.
- Do you answer emergency calls at night and on weekends?
- Yes. K&J Tree Works takes calls 24/7 at (425) 223-7904. When we can be on site depends on safety conditions, storm demand and crew availability, so we do not promise a set arrival time. Regular business hours are Monday through Saturday, 8 AM to 5 PM. For injuries, fire or a sparking line, call 911 first.
- Does homeowners insurance pay for tree removal?
- Often, when a covered storm causes a tree to damage your home, garage or another covered structure, subject to your deductible and limits. Many policies treat getting the tree off the structure as part of the home claim, while cutting up and hauling the wood away has a smaller separate limit, such as $1,000 per storm and $500 per tree in the standard policy form. Not every insurer splits it this way, so ask your adjuster. Cleanup of a tree that fell without hitting anything usually is not covered, although some policies cover removal when a tree blocks a driveway or accessibility ramp. Your insurer makes the coverage decision.
- Do I have to wait for an adjuster before removing a tree from my roof?
- Do not delay work needed to keep people safe or prevent further damage. Call your insurer promptly, ask what emergency work it can authorize, document the damage from a safe spot, and keep receipts. Washington's Insurance Commissioner advises waiting on permanent repairs until your insurer has seen the damage and you have agreed on repairs.
- Does K&J bill my insurance company or talk to my adjuster?
- No. K&J provides a written scope and estimate, followed by a contract, invoice and receipt. We typically do not communicate directly with insurance adjusters. Clients usually pay our invoice and submit the documentation to their insurer for review and any reimbursement available under their policy. Reimbursement is not guaranteed.
- A neighbor's tree fell on my house. Whose insurance pays?
- Your own homeowner insurer will often handle the claim, and you pay your deductible. If the neighbor was at fault, your insurer may try to recover from the neighbor's insurer, but that can be hard to prove.
- What does emergency tree removal cost?
- It depends on the tree's size and condition, what it is resting on, access, rigging, utilities and cleanup. Urgent storm work is often more complex than a planned removal. K&J provides a written scope and estimate before work begins.
- Can I wait if the tree is not on my house?
- If a fallen tree is not threatening a structure, blocking access or touching a line, it can often wait for a scheduled removal. A tree resting on another tree, a fence or partly uprooted can shift further, so keep clear and call for an assessment.
Tree Down? Call (425) 223-7904
K&J Tree Works helps homeowners across Snohomish and King County after storms. We take calls 24/7; on-site timing depends on safety conditions and crew availability. Regular business hours are Monday through Saturday, 8 AM to 5 PM. If anyone is hurt or a power line is involved, call 911 or your utility first.